I don't know whether you have heard about our REG original questions: CPA Regulation. Nevertheless, I still want to make a brief introduction about our REG answers real questions for the sake of your own benefits. Do you think I am a little bit pretentious? Well, I would like to extend my sincere gratitude if you do not make such an early conclusion. Upon reading the following text, all your doubts will be dissipated.

Simulation for the App version
As is known to all, simulation plays an important role in the final results of the customers. The simulation opportunity offered by the App version of our REG original questions: CPA Regulation of course also is of great significance for those who are not so familiar with the environment of the test. By simulation of REG answers real questions, we refer to simulate the environment, procedure and contents for the test so that the customers can be acquainted with what will happen in the real test. As it is highly similar to the AICPA REG real exam, customers can explore the most suitable way to answer the questions in the test. For instance, they can decide what kind of questions of REG exam cram to do first and what to do in the end. In this way, they can make full use of the time to answer questions that they are more likely to do one hundred percent correct.
Many benefits for the PDF version
Once you have chosen the PDF version for our REG original questions: CPA Regulation, you will enjoy the continuous surprise from then on. First and foremost, there is demo in the PDF version and customers are allowed to download it to have the pre-trying experience. Therefore, the customers have a better understanding about our REG answers real questions ahead of time so that the customers can decide if our exam files are suitable or not. Secondly, you can print the PDF version of our REG exam prep: CPA Regulation into the paper version so that the customers can make notes for their later review. Thirdly, the PDF version of REG original questions: CPA Regulation is convenient to look through, which can greatly benefit our customers.
Instant Download REG Exam Braindumps: Upon successful payment, Our systems will automatically send the product you have purchased to your mailbox by email. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
High pass rate
According to the statistics recorded, the general pass rate for our REG original questions: CPA Regulation is 98% to 99%, far beyond that of other exam files. As a result, our REG answers real questions gradually win a place in the study materials providing. People who have used our REG exam bootcamp can pass the exam much easier than others, which is the essential reason why more and more people turn to the help from our REG PDF VCE. As far as the high pass rate is concerned, it really acts as a driving force for those who are keen on the success in the exams. As our REG exam cram are bestowed with a high pass rate, the customers using our exam materials will have more confidence to get good grades in the exams, which in turn encourage them to have a better performance.
AICPA REG Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Federal Taxation of Property Transactions | 5-15% | - Gains and losses on disposition of assets - Basis, cost recovery (depreciation and amortization) |
| Topic 2: Business Law | 15-25% | - Agency, contracts, and debtor-creditor relationships - Business structures and federal business regulations - Legal duties and responsibilities in business transactions |
| Topic 3: Federal Taxation of Individuals | 22-32% | - Tax filing requirements and procedures - Individual taxable income and tax compliance - Adjustments, deductions, exemptions and credits |
| Topic 4: Federal Taxation of Entities | 23-33% | - Tax compliance for corporations, partnerships, LLCs, and S corporations - Entity-level tax planning and reporting requirements |
| Topic 5: Ethics, Professional Responsibilities and Federal Tax Procedures | 10-20% | - Federal tax procedures, disclosures, penalties, and appeals - Ethics and responsibilities in tax practice (Treasury Department Circular 230) - Licensing and disciplinary systems for CPA practice |
AICPA CPA Regulation Sample Questions:
Cobb, an unmarried individual, had an adjusted gross income of $200,000 in 1990 before any IRA
deduction, taxable social security benefits, or passive activity losses. Cobb incurred a loss of $30,000 in
1 990 from rental real estate in which he actively participated. What amount of loss attributable to this
rental real estate can be used in 1990 as an offset against income from nonpassive sources?
- A. $30,000
- B. $12,500
- C. $0
- D. $25,000
Correct Answer: C 🗳️
Explanation: Only visible for TestValid members. You can sign-up / login (it's free).
In 19X4, Smith, a divorced person, provided over one half the support for his widowed mother, Ruth, and
his son, Clay, both of whom are U.S. citizens. During 19X4, Ruth did not live with Smith. She received
$ 9,000 in Social Security benefits. Clay, a 25 year-old full-time graduate student, and his wife lived with
Smith. Clay had no income but filed a joint return for 19X4, owing an additional $500 in taxes on his wife's
income. How many exemptions was Smith entitled to claim on his 19X4 tax return?
- A. 3
- B. 1
- C. 2
- D. 4
Correct Answer: C 🗳️
Explanation: Only visible for TestValid members. You can sign-up / login (it's free).
John and Mary were divorced in 1991. The divorce decree provides that John pay alimony of $10,000 per
year, to be reduced by 20% on their child's 18th birthday. During 1992, John paid $7,000 directly to Mary
and $3,000 to Spring College for Mary's tuition. What amount of these payments should be reported as
income in Mary's 1992 income tax return?
- A. $8,600
- B. $8,000
- C. $5,600
- D. $10,000
Correct Answer: B 🗳️
Explanation: Only visible for TestValid members. You can sign-up / login (it's free).
In the current year Jensen had the following items: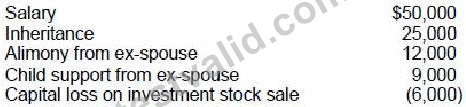
What is Jensen's AGI for the current year?
- A. $84,000
- B. $44,000
- C. $59,000
- D. $62,000
Correct Answer: C 🗳️
Explanation: Only visible for TestValid members. You can sign-up / login (it's free).
Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable
income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own
and was Tom's dependent.
Determine the amount of income or loss, if any that should be included on page one of the Moores' 1994
Form 1040.
In 1992, Joan received an acre of land as an inter-vivos gift from her grandfather. At the time of the gift,
the land had a fair market value of $50,000. The grandfather's adjusted basis was $60,000. Joan sold the
land in 1994 to an unrelated third party for $56,000.
- A. $2,000
- B. $900
- C. $2,500
- D. $500
- E. $1,500
- F. $55,000
- G. $0
- H. $50,000
- I. $3,000
- J. $10,000
- K. $75,000
- L. $1,250
- M. $1,000
- N. $25,000
- O. $1,300
Correct Answer: G 🗳️
Explanation: Only visible for TestValid members. You can sign-up / login (it's free).

 Parker

 Debby
 Kennedy

 Larry
 Horace

 Neil
 Dorothy
 Eileen
 Harold
 Lionel
 Lynn
 Pag
 Roxanne
 Eli
 Carl
 Maurice